A property owner in New Jersey had homeowners insurance coverage through a regional carrier, Selective Insurance of America, when his home was hit by a high-wind event on Dec. 9, 2025.
After notifying the insurer and submitting a claim, the policyholder expected to receive a fair settlement for the obvious and extensive damages. However, after the carrier insurance adjuster and an engineer inspected the damage, a desk adjuster for the carrier issued a full claim denial.
The insurance adjuster’s property inspection and subsequent engineer report cited wear and tear as the source of the damage, and on June 1, 2026, the carrier denied the roof claim altogether.
Denials like this aren't unusual. With approximately 50% of property insurance claims denied with zero payout to claimants, this policyholder found himself on the receiving end of a wrongful denial, which has become the default for many insured property owners. Not every claim closed without payment is wrongly denied, but a denial isn't always the final word.
On June 2, 2026, the policyholder reached out to Prabhdeep Singh’s Trenton, NJ office and retained Tiger Adjusters. Licensed Public Adjuster Michael Steinbrecher reviewed the claim documentation, including the engineering report.
Although the engineer concluded that the roof was “at or past its effective service life,” the engineer also identified additional shingle damage not documented during a prior inspection conducted in 2021 and expressly acknowledged that he “could not discount that this recent wind contributed to the damage observed at the . . . residence.” This finding raised questions about Selective’s attribution of the damage solely to deterioration and installation issues.
After challenging the engineer's findings and receiving repeated denials from the carrier's desk adjuster, Michael escalated the dispute to the carrier's internal appeals department. The appeals department concluded that only three shingles sustained damage from a covered event and that localized repairs were sufficient. At that stage, the carrier offered the policyholder $2,441.10 for the claimed damage.
Michael continued challenging that determination. Working with an experienced roofing contractor, he obtained additional evidence showing that the damaged shingles could not be repaired without causing further damage to the surrounding roof. With these findings, Michael asked the carrier to reconsider its position and approve replacement of the remaining roof.
After the claim was escalated to a supervisor for review, on September 15, 2026, the carrier approved a full roof replacement.
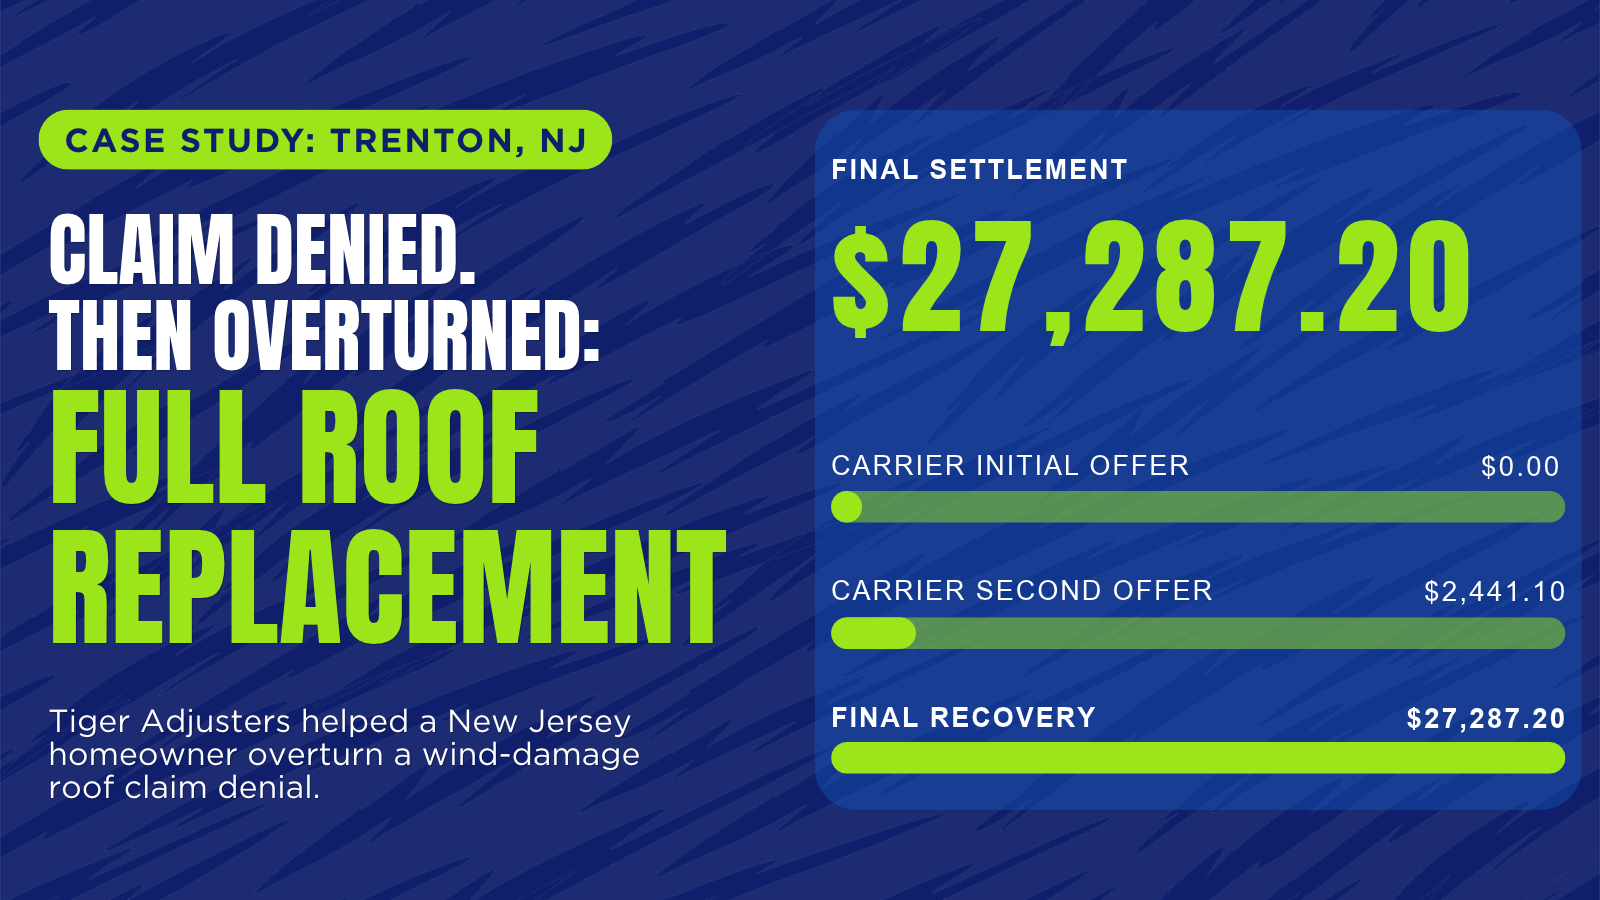
After the initial claim denial, which offered the policyholder $0 for roof repairs, Michael appealed the decision, which led to an offer of $2,441.10, then continued the appeal, resulting in a final settlement of $27,287.20 over about three and a half months.
This turnaround helped the policyholder replace the roof with the insurance proceeds, subject to the policy's deductible and terms, instead of paying for the repairs on his own.
At Tiger Adjusters, helping you recover what your policy covers after a loss is our top priority. Need help negotiating a fair settlement on your insurance claim? Get in touch.